Office furniture normally qualifies as plant and machinery, which means most UK businesses can claim capital allowances on desks, chairs and storage bought for a workspace. What follows covers which items count, the rates that apply, how to structure a claim, a worked example with real numbers, and the mistakes that cost businesses money every year.
Key Takeaways
Office furniture normally qualifies as plant and machinery, and AIA or full expensing usually gives the fastest tax relief when the paperwork is right.
| Point | Details |
|---|---|
| Furniture usually qualifies | Desks, chairs, and storage are normally plant and machinery, claimable under AIA or WDA. |
| AIA gives fastest relief | 100% relief up to the £1 million annual limit, best allocated against special-rate assets first. |
| Full expensing is company-only | Requires new and unused main-rate assets; second-hand furniture is excluded. |
| Segregate fit-out costs | Get itemised contractor schedules to separate furniture from structural building work. |
| Furnitureforbusiness supports procurement | Itemised quotes and bulk pricing on chairs and desks help keep capital allowances claims clean. |
Table of Contents
- What counts as office furniture for capital allowances?
- Which capital allowances and rates apply to office furniture
- How to claim capital allowances on office furniture
- Worked example: AIA versus writing-down allowances
- Common pitfalls that cost businesses tax relief
- When to handle this yourself and when to call an accountant
- The practical approach worth taking
- How Furnitureforbusiness supports capital allowances planning
- Where to check the official rules
- Frequently asked questions
- Sources
What counts as office furniture for capital allowances?
Desks, ergonomic chairs, filing cabinets, freestanding partitions, and moveable meeting tables all sit squarely within HMRC’s definition of plant and machinery. IT equipment bought alongside furniture, such as monitor arms or server racks, usually qualifies too when it’s treated as plant rather than part of the building.
Not everything in a fit-out counts. Land, structural elements like load-bearing walls, and items used purely for entertainment fall outside the scheme. Leased furniture is normally excluded unless it is on hire purchase, because you need to own the asset to claim.
Then there are “integral features”: things like lifts, air conditioning, and electrical systems, which sit in a separate special-rate category rather than the main pool. Some fitted furniture, particularly built-in reception counters or bespoke joinery, can blur this line depending on how it’s fixed to the building.
- Qualifying: desks, task chairs, executive seating, storage units, meeting tables, freestanding partitions
- Non-qualifying or restricted: leased items (unless hire purchase), structural building work, land
- Grey area: integral features, fitted or built-in furniture connected to the building’s fabric
Pro Tip: Ask your contractor for an itemised cost schedule before work starts. Splitting furniture and plant costs from structural spend at invoice stage saves a much harder job later, and specialist commentary on furniture classification backs this up as standard practice for fit-outs.
Which capital allowances and rates apply to office furniture
Four mechanisms cover most furniture purchases, and picking the right one changes how quickly you see the tax benefit.
The Annual Investment Allowance (AIA) gives 100% relief on qualifying plant and machinery, including furniture, up to the annual limit of £1 million as of 2026. Full expensing works similarly but applies only to companies buying new and unused main-rate plant and machinery, giving 100% first-year relief without touching your AIA headroom. Writing-down allowances (WDA) apply once AIA or full expensing has been used up, or where neither applies: the main pool typically gets 18% on a reducing balance, while the special-rate pool gets 6%.
Certain special-rate items, mainly integral features, can attract a 40% first-year allowance for companies, with the remaining balance carried into the 6% special-rate pool.
Before allocating anything, run through this:
- Confirm the current AIA limit and rates on GOV.UK, since these figures are reviewed periodically
- Check whether each asset is main-rate or special-rate before you allocate AIA
- Remember full expensing needs new and unused assets bought by a company, not a sole trader or partnership
- Model both routes if you’re near the AIA limit, since Saffery’s practitioner guidance notes the choice affects cash flow timing, not just the total relief
How to claim capital allowances on office furniture
Claiming isn’t complicated once the paperwork is in order, but the sequence matters.
- Identify every qualifying asset bought in the accounting period, from chairs to storage units.
- Segregate costs where furniture was bought as part of a larger fit-out invoice, separating plant from structural work.
- Decide your relief route: AIA, full expensing (companies only, new and unused assets), or pooling with WDA.
- Allocate AIA strategically, usually against assets that would otherwise sit in the slower special-rate pool.
- Record the claim in your company tax return (CT600) or self-assessment return, in the period the cost was incurred.
Keep these on file in case HMRC asks questions later:
- Invoices showing whether items were new or used
- Delivery notes and dates matching the accounting period
- Itemised contractor cost schedules for fit-out work
- VAT treatment (net or gross figures used consistently)
- Hire purchase agreements, where relevant
Eligibility differs slightly by structure. Sole traders and partnerships can claim AIA but not full expensing, since that relief is restricted to companies. Partnerships involving a corporate partner face additional restrictions worth checking with an accountant before you assume AIA applies in full.
Worked example: AIA versus writing-down allowances
Picture a company spending £40,000 on new desks and chairs, plus £20,000 on a fitted reception counter where £8,000 is treated as an integral feature.
Route one: allocate AIA to the £40,000 of furniture, getting 100% relief immediately. The £8,000 integral feature goes into the special-rate pool, either claiming the 40% first-year allowance or the 6% WDA.
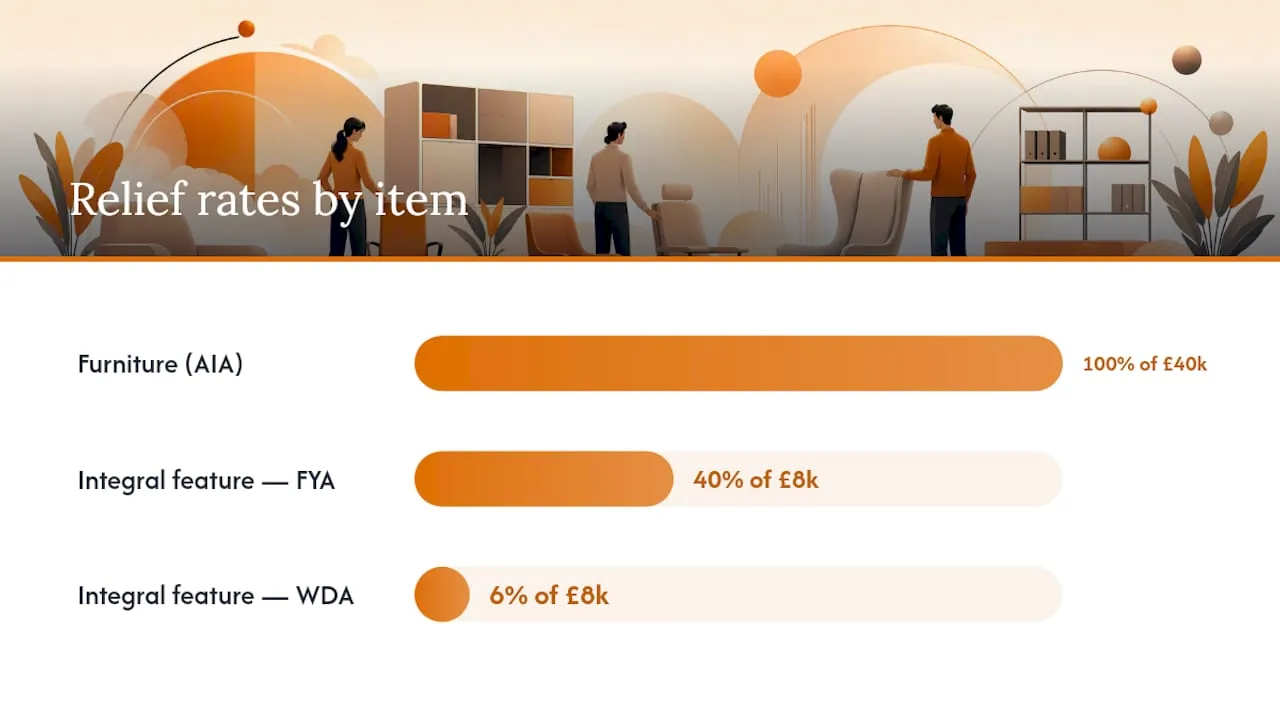
Substitute your own tax rate and confirm current AIA headroom before relying on any specific savings figures, since availability depends on what else you’ve already claimed that year.
Common pitfalls that cost businesses tax relief
Most lost relief comes down to paperwork, not eligibility.
- Lumping furniture costs into one contractor invoice with structural work, making segregation impossible later
- Treating fixtures as building work by default, pushing them into slower Structures and Buildings Allowance rates
- Buying a property without a section 198 election to agree fixture values with the seller, risking the allowances entirely
- Claiming for leased furniture that isn’t actually owned
- Assuming second-hand furniture qualifies for full expensing, when that relief needs new and unused assets
Each mistake either loses relief outright or triggers a slower claim than necessary.
Pro Tip: If you’re buying a property or planning a major refit, commission a pre-contract capital allowances review. It costs far less than the relief you’d otherwise leave on the table.
When to handle this yourself and when to call an accountant
Straightforward purchases (a batch of desks, some task chairs) are usually simple enough to claim without help: gather invoices, check AIA headroom, and record the entry.
- Get specialist advice for property purchases, mixed new/used asset lists, large fit-outs, or anything involving a section 198 election
- Also flag it to your accountant if integral features make up a significant chunk of spend
The practical approach worth taking
Build cost segregation into procurement from day one, not as a scramble at year-end. Ask contractors for itemised schedules before signing anything, and treat tax relief as a cash-flow tool rather than the reason you’re buying furniture.
Quality and ergonomics still matter more than the tax line. A durable, well-specified chair that lasts a decade delivers more value than a cheap one bought purely to use up AIA headroom this year.
How Furnitureforbusiness supports capital allowances planning
Getting the tax treatment right starts with getting the paperwork right, and that means clear, itemised quotes rather than one lump-sum invoice for an entire fit-out. Furnitureforbusiness provides itemised pricing across office chairs and office desks, which makes segregating furniture costs from any structural work straightforward when it comes to your claim.
Bulk order pricing applies across ranges, delivery to the UK mainland is free, and returns are easy if a specification needs adjusting once your fit-out is under way. Whether you’re replacing a handful of task chairs or fitting out an entire floor, browsing the office desks range now gives you real figures to take straight into your capital allowances calculation.
Where to check the official rules
Rates and limits shift periodically, so confirm figures directly before filing.
- Capital allowances overview and what you can claim on, GOV.UK
- HS252 helpsheet on allowances and balancing charges, GOV.UK
- CA23084 HMRC internal manual and Croner’s furniture commentary
Frequently asked questions
Does office furniture always qualify for capital allowances?
Most freestanding furniture qualifies as plant and machinery, but built-in or fitted items connected to the building’s structure sometimes fall into the integral features category instead, which changes the rate you claim.
Can sole traders claim full expensing on office furniture?
No. Full expensing is restricted to companies buying new and unused main-rate plant and machinery.
What happens if I buy second-hand office furniture?
Second-hand furniture can still qualify for AIA or writing-down allowances, but it’s excluded from full expensing, which specifically requires new and unused assets.
Do I need an accountant to claim capital allowances on office furniture?
Simple purchases, a few desks or chairs, are usually manageable yourself with clear invoices. Larger fit-outs, property purchases, or anything involving integral features are worth a specialist review before you file.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.